Best Budget

Screenshots
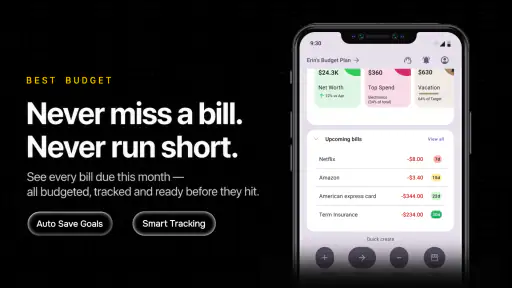
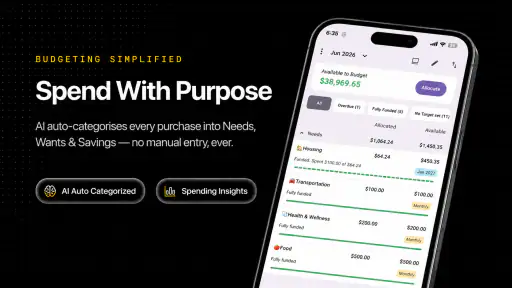
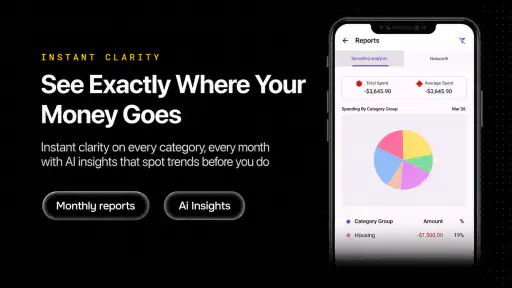
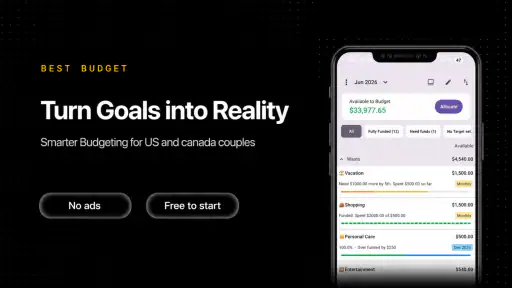
Details
- Rating
- 0.00 reviews
- Version
- 2.1.4
- Developer
- CREXIN Technologies
Analysis by Norviv
Managing money is rarely difficult because people cannot add and subtract. The real problem is keeping a clear picture of several small decisions at once: a coffee here, a subscription there, an unexpected bill, and a savings goal that keeps moving further away. Best Budget, a free finance app from CREXIN Technologies, is designed around that everyday problem. I approached it as a practical budgeting tool rather than a complete banking replacement, and that distinction matters when deciding whether it belongs on your phone.
My first impression is that its purpose is easy to understand. It brings spending awareness, budget planning, debt reduction and saving into one place instead of leaving those tasks scattered across banking apps, notes and spreadsheets. That makes it most appealing to someone who wants a more deliberate routine without immediately committing to a complicated financial system. The current release is version 2.1.4, and the app is intended for devices running Android 8.0 or later.
How Best Budget feels during ordinary use
The strongest way to use this app is as a short daily check-in. I would not treat it as something to open only when a bill is due. The useful habit is to record or review spending while purchases are still fresh, then compare the result with the limits you set. That turns the app from a passive ledger into a decision-making tool.
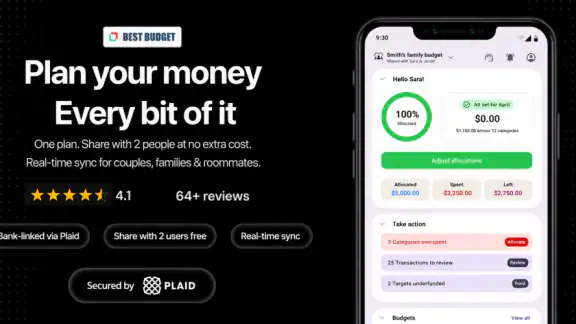
Its focus on personal finance tracking should suit people who want to answer simple questions quickly: How much have I spent in a category? Is my discretionary money disappearing too early in the month? Can I make an extra debt payment without damaging my basic budget? The value comes from seeing these questions together rather than solving each one separately.
A realistic example would be a user paid near the start of the month who sets aside money for rent, transport, groceries and debt. After several unplanned lunches, the grocery and flexible-spending limits begin to compete. Instead of waiting for the bank balance to feel alarming, the user can review the pattern, reduce optional spending for the remaining days and protect the debt payment. That is a modest workflow, but it is exactly the kind of repeated decision where a budget app earns its place.
I also like the idea of separating a target from a wish. “Save more” is vague; a savings goal connected to a regular review gives the user something concrete to protect. The same applies to debt. A debt plan is more useful when it changes what I do with this week’s money, not merely when it displays a large total that feels discouraging.
What feels quick, and what may slow the routine
For a finance app built around entries, categories and plans, I would expect the basic screens to feel light on a modern phone. Best Budget does not present itself as a large banking platform with a broad collection of financial services, so its everyday workload should be more manageable than an app that constantly handles accounts, markets and transactions in real time. That makes it a reasonable candidate for quick manual check-ins.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
However, perceived speed is not only about opening time. A budget tool feels fast when recording a purchase takes less effort than ignoring it. If entering every transaction becomes repetitive, the app can lose its usefulness even if the interface itself responds promptly. My practical advice is to begin with only the categories that influence your decisions. A smaller, meaningful setup is likely to remain usable longer than an elaborate structure requiring constant maintenance.
Heavy use would probably come during the first setup, a monthly reset or a serious debt review. Those moments involve more thought than a normal daily entry. I would plan to build the budget when I have enough time to check recurring obligations and realistic spending habits, rather than trying to configure everything during a rushed commute. The app can support the process, but it cannot decide whether a limit reflects real life.
One non-obvious trade-off is precision versus consistency. Tracking every tiny distinction may look responsible, but it can make the routine fragile. For many people, a slightly broader category that is updated regularly will reveal more than a perfect category system abandoned after a week. Best Budget is most useful when its structure matches the way I actually make decisions.
Stability and recovering from a missed day
Financial records deserve a calmer standard of reliability than a casual notes app. A missed entry can distort a budget, and a forgotten debt payment can have consequences outside the app. For that reason, I would use Best Budget as a planning and awareness companion while continuing to treat official bank statements, lender accounts and payment confirmations as the final authority.
The app’s modest install footprint in the store ecosystem is worth viewing neutrally. It is not a reason to dismiss it, but it also means I would personally spend a little time testing my routine before relying on it as the only place where important financial plans live. I would make sure my categories, balances and goals still make sense after closing and reopening the app, and I would keep essential account information available elsewhere.
Recovery is especially important after a missed week. The wrong response is to abandon the budget because several purchases are unrecorded. A better approach is to reconstruct the period from receipts and bank activity, enter the larger transactions first, and then mark the remaining amount as an adjustment if exact reconstruction is not worth the effort. That workflow protects the habit without pretending the record is more precise than it is.
This is also where I see a limitation common to manual budgeting: the quality of the result depends on the quality of the input. If Best Budget does not fit the way you obtain transaction information, the app may become an extra administrative layer. Someone who wants automatic financial synchronization, investment monitoring or a highly automated account dashboard may be better served by a different category of service.
Using it on older or modest devices
Best Budget supports Android 8.0 and later, which makes it accessible to people who are not using a recent flagship phone. That is helpful for a finance utility because many users want to install it on an older spare device or keep their main phone for years. The app’s core purpose also suggests a lighter workload than media-heavy or graphics-intensive software.
Still, operating-system support should not be confused with identical performance on every device. An older phone with limited free storage, aggressive battery management or many background processes may make any app feel less responsive. I would keep enough space available, update the operating system where practical, and avoid judging the app while the phone is already struggling with several unrelated tasks.
For someone using an older device, the most sensible test is practical rather than technical: can I open the app, review the current budget, add a purchase and return to the summary without friction? If yes, the device is probably adequate for the way this app is meant to be used. If the phone is so old that ordinary form entry is unpleasant, a simple spreadsheet or paper method might actually be faster.
The age rating is Everyone, so the presentation is positioned for a broad audience rather than a narrowly restricted financial product. That does not remove the need for adult judgment around debt or household money, but it does make the app approachable for families, students and first-time budgeters who want to learn the basics without a specialized investment interface.
Where it fits beside familiar alternatives
The usual alternatives are a spreadsheet, a notes app, a bank’s built-in spending view or a more automated budgeting service. A spreadsheet offers maximum flexibility, but it also asks the user to design formulas, categories and summaries. A notes app is quick, yet it rarely helps turn a list of purchases into a coherent plan. Bank tools can be convenient for account activity, but they may not be designed around personal goals such as debt reduction or deliberate saving.
Best Budget sits between those options. It should be more structured than free-form notes and less demanding than building a financial workbook from scratch. That middle position is its main appeal. I would choose it for a person who wants a dedicated budgeting space but does not need a full investment dashboard or a bank replacement.
The trade-off is that convenience may depend on how much information the user must maintain. If your priority is automatic categorization across several accounts, a service built specifically around account connections may save more time. If your priority is complete control over formulas and custom reports, a spreadsheet may win. Best Budget makes more sense when the goal is a focused, repeatable budgeting routine rather than unlimited customization.
Costs, version and practical expectations
The app is free to install, while in-app purchases are listed from six dollars to ninety-six dollars per item. That range makes it important to approach optional spending carefully. I would begin with the free experience, establish whether the basic workflow actually improves my habits, and only then consider paying for anything that directly solves a problem I have encountered.
In other words, do not assume that a paid option automatically creates better financial discipline. A person who does not review transactions will not be rescued by an additional purchase. The most valuable test is whether the free version makes weekly decisions clearer and whether the routine remains comfortable after the novelty disappears.
The app was released on March 9, 2026, and the listed version is 2.1.4. Those details place it in a relatively early stage of its public life, so I would keep expectations realistic about how mature the overall experience may feel compared with long-established finance platforms. That is not a criticism of the developer, CREXIN Technologies; it is simply a reason to evaluate the app by the workflow it currently provides rather than by promises about a future roadmap.
Who should use it, and who should skip it
I think Best Budget is a good match for someone whose money feels scattered but whose needs are still straightforward. It can be particularly useful for a new worker learning to divide income, a household trying to control flexible spending, or anyone who wants debt and savings to appear in the same planning conversation. The app’s broad finance focus gives those users a practical starting point.
I would also recommend it to people who prefer active control. Some users enjoy checking their decisions and making adjustments; they do not want an automated system to hide the reasoning behind a number. For them, the act of entering and reviewing information can become part of the accountability process.
I would skip it if you need a complete banking workspace, live investment analysis, complex business bookkeeping or guaranteed automation across many financial accounts. It is also a poor fit if you know you will not maintain entries. In that situation, an automatic bank-based tool may be more realistic, even if it offers less personal control.
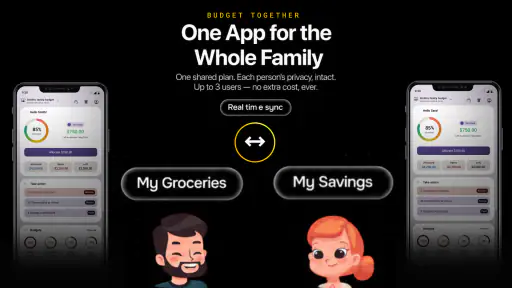
Families should decide in advance how they will handle shared expenses. A single budget can become confusing when several people record purchases differently. Agreeing on category names and a weekly review time is more important than creating a long list of categories. For a solo user, the setup can stay simpler; for a household, consistency becomes the real challenge.
My performance verdict
Best Budget comes across as a focused budgeting companion rather than an all-purpose financial command center. Its strongest performance is likely to appear in short, repeated sessions: checking a category, recording a purchase, reviewing a debt target or protecting a savings contribution. That narrow purpose is a strength because it keeps the financial conversation understandable.
Its limitations are equally clear. Manual discipline can become friction, older devices may vary in responsiveness, and users seeking broad automation or advanced financial analysis should look elsewhere. I would not install it expecting the app to make difficult choices for me. I would install it expecting a clearer place to make those choices myself.
With over ten thousand installs and an Everyone rating, it is accessible enough for a broad audience, while the free entry point makes experimentation straightforward. My recommendation is to try it with one month, a few meaningful categories and one specific goal. If that small workflow helps you notice spending earlier and make better trade-offs, Best Budget is doing its job.
The best reason to choose Best Budget is not the promise of perfect financial control; it is the chance to turn vague intentions into a routine you can actually repeat. For users who want that hands-on approach, this app is worth considering. For those who want their finances handled automatically in the background, a more connected alternative will probably be the better fit.
Frequently Asked Questions
01What is Best Budget, and what can I use it for?
Best Budget is a personal finance app designed to help you organize income, expenses, bills, and savings goals in one place. After reviewing its main functions, it is most useful for people who want a clearer overview of daily spending and monthly planning. You can generally use it to categorize transactions, monitor budgets, and identify areas where your spending may be higher than expected.
02Is Best Budget suitable for beginners who have never used a budgeting app?
Yes, Best Budget is intended to be approachable for users with different levels of financial experience. Its budgeting concept is straightforward: enter or track your income, assign spending to categories, and compare actual expenses with planned limits. Beginners should still take time to configure categories and recurring payments correctly, because the accuracy of the reports depends largely on the information entered into the app.
03Does Best Budget connect directly to bank accounts and credit cards?
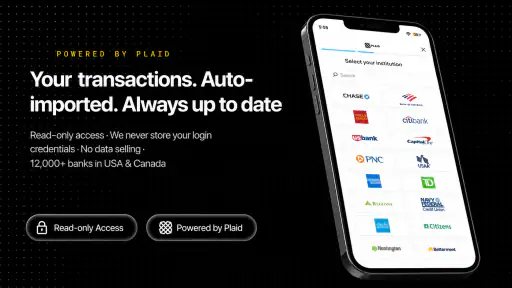
Bank connectivity can vary depending on the app version, region, and the financial institutions supported by the service. Before downloading, users should check the current store description and privacy information to confirm whether automatic synchronization is available. If direct connections are not supported for your bank, you may need to add transactions manually or import them using an available supported method.
04Is my financial information safe when using Best Budget?
Because a budgeting app may contain sensitive information about income, purchases, and financial habits, privacy should be reviewed before use. Check whether Best Budget offers encryption, secure account access, backup controls, and clear data-handling policies. Avoid entering complete banking credentials unless the app uses a reputable secure connection, and protect your account with a strong password or biometric authentication when available.
05Does Best Budget cost money, and are there any in-app purchases?
The cost of Best Budget may depend on the platform, subscription plan, and features included in the current release. Some budgeting apps provide a free basic version while reserving advanced reports, synchronization, exports, or unlimited categories for premium users. Before installing, review the Google Play or App Store listing carefully for trial terms, recurring charges, and cancellation requirements so there are no unexpected costs.


